Flood Insurance
Flood Insurance
Get a flood quote
Why add flood
A separate policy from your homeowners.
Written through the NFIP or by private-market carriers.
Rated on the property.
Flood zone, elevation, foundation type, and rebuilding cost all go into the rate.
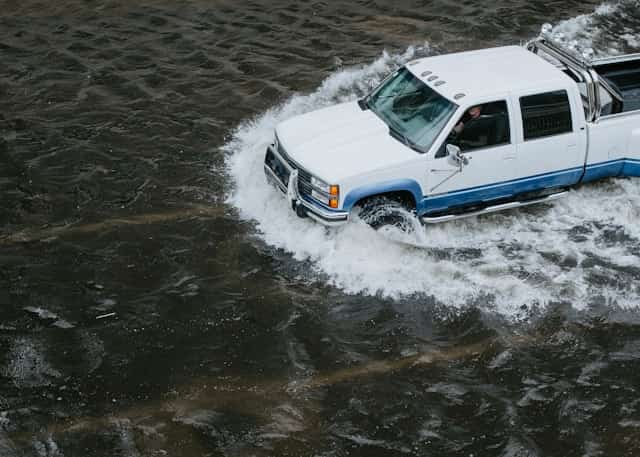
One inch can run ~$25,000 in damage.
FEMA's estimate for a single inch of floodwater in a 1,000 sq ft home.
Nearly a third of claims are outside high-risk zones.
Heavy rain and overwhelmed drainage don't check FEMA maps. FEMA puts it at 29% of NFIP claims — properties officially mapped as moderate-to-low risk.
A policy can't be bought during a storm.
NFIP policies carry a 30-day waiting period before the policy takes effect. Private carriers like Neptune can be as short as 10 days. Either way, binding closes once a flood warning is issued — the time to buy is before the cone.
Claim-share figure: FEMA, floodsmart.gov
Flood policies
Four kinds of flood policy.
For homeowners, unit owners, condo boards, commercial owners, and high-value properties.
Residential flood
NFIP or private market
A flood policy for single-family homes, condos, townhouses, and rentals.
- NFIP and private-market options
- Required by federally backed mortgages in high-risk zones
- Rated by zone, elevation, and construction type
Commercial flood
Business and investment real estate
A flood policy for business properties, apartment buildings, hotels, retail, and investment real estate.
- NFIP and private-market options
- Rated by zone, elevation, and construction type
- Multi-location scheduling across a portfolio
Condo association
RCBAP — HOA / board placement
The NFIP's building-wide policy for residential condo associations — purchased by the HOA or property manager.
- Often required by federally-backed mortgages in high-risk zones
- Separate from each unit owner's own flood policy
Excess flood
Above a primary flood policy
A separate policy written above a primary NFIP or private flood policy.
- Common on high-value coastal and luxury properties
- Written over an existing NFIP or private primary flood policy
Not sure which product fits? Talk to an advisor
Quote prep
What you'll need.
Property information
- Property address
- Year built
- Number of floors
- Foundation type
- Building square footage
Flood zone information
- Flood zone designation
- Elevation certificate (if available)
- Previous flood claims
Limits and deductible
- Building limit requested
- Contents limit requested
- Deductible
Prior policy information
- Current flood policy details
- Policy expiration date
- Claims history
- Annual premium
Get a quote
Compare carriers. No obligation.
Or call (504) 315-4536
Related policies
Flood is one policy. Here are the others.
Most paired with flood
Homeowners Insurance
A separate policy from flood. Gulf Coast properties typically carry both.
Commercial Property
Rated on the building itself: location, construction, age, roof, and fire protection.
ExplorePersonal Umbrella
Written above your home and auto policies.
ExploreAuto Insurance
Rated on your drivers, vehicles, garaging address, and driving history.
ExploreWant it all under one advisor? Call (504) 315-4536
Flood Insurance by area
Get in touch
Multiple ways to connect.
FAQ
Frequently asked questions.
Answers to the questions Gulf Coast property owners ask us most often about flood.
Still have questions?
Call (504) 315-4536Ready to compare?
An NFIP policy typically takes effect 30 days after purchase. Private-carrier waiting periods vary by carrier and risk — Neptune runs as short as 10 days on qualifying policies. Loan-close and map-revision exceptions apply.
Need to file a claim?
Here to help you through the claims process.
Mon–Fri · 7:30a–5:00p CT